Pre-Tax Commuter Benefits: What Employees Need to Know Before These Savings Slip Away
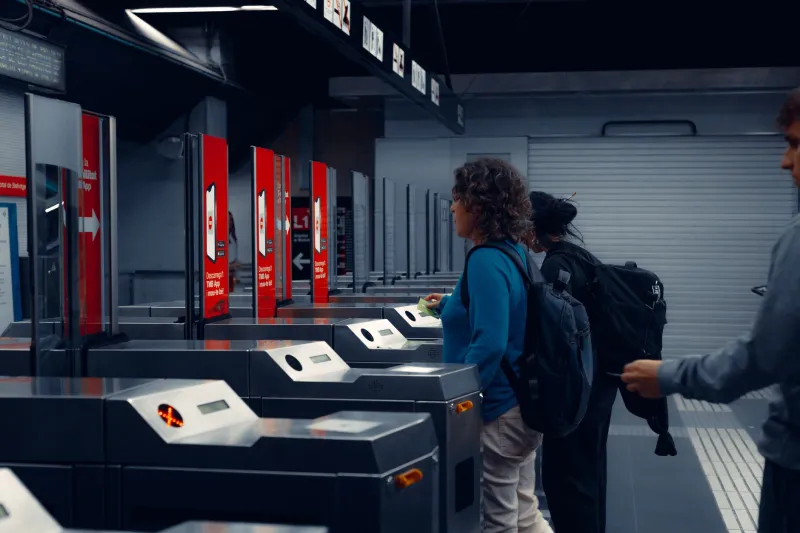
For most working Americans, the daily commute is simply a cost of doing business—an unavoidable line item in the household budget. What many employees don't realize, however, is that a federally sanctioned benefit program exists specifically to reduce that burden. Commuter benefit accounts allow workers to pay for qualifying transit and parking expenses using pre-tax dollars, effectively lowering their taxable income and keeping more money in their paychecks.
Despite their practical value, commuter benefits remain among the least understood offerings in the workplace benefits landscape. And with ongoing legislative and regulatory changes creating uncertainty around contribution limits and employer obligations, the time to pay attention is now.
How Commuter Benefits Actually Work
Commuter benefits are governed primarily by Section 132(f) of the Internal Revenue Code. Under this provision, employees can exclude a set amount of their wages from federal income tax each month when those funds are used for qualifying commuting expenses. The two main categories are:
- Transit passes and vanpool costs: This covers bus passes, subway fares, commuter rail tickets, and qualified vanpool arrangements.
- Qualified parking: This applies to parking at or near your workplace, or at a location from which you commute via transit.
As of 2024, the IRS allows employees to exclude up to $315 per month for transit and vanpool expenses and an additional $315 per month for qualified parking—for a potential combined annual exclusion of $7,560. These limits are adjusted periodically for inflation, though they don't always keep pace with the actual cost of commuting in high-density metropolitan areas.
Employers may offer these benefits in two ways: by providing benefits directly (such as subsidized transit passes) or through a salary reduction arrangement, where employees elect to have a portion of their pre-tax wages deposited into a commuter benefit account. In some cases, employers offer both.
Why Awareness Remains Stubbornly Low
Despite being a legitimate federal tax benefit, commuter programs are frequently absent from open enrollment conversations and employee onboarding materials. Several factors contribute to this gap.
First, unlike health insurance or retirement accounts, commuter benefits don't carry the same cultural weight in discussions about compensation. They're rarely highlighted in job postings and often buried in benefits documentation that employees receive and quickly set aside.
Second, the benefit structure can vary considerably from one employer to another. Some organizations offer robust, employer-subsidized programs. Others provide only the minimum required framework, leaving employees to navigate enrollment largely on their own. Workers at smaller companies may find that no formal program exists at all—though individual employees in some states may still be able to claim deductions through state-level programs.
Third, the use-it-or-lose-it structure of many commuter benefit accounts discourages some employees from enrolling. Unlike Health Savings Accounts, funds in transit benefit accounts that go unspent typically do not roll over indefinitely. This creates a perception of risk that, while understandable, often leads workers to forgo a benefit they could otherwise use reliably each month.
Policy Changes Putting These Benefits at Risk
The commuter benefit landscape has not been static. Over the past several years, a combination of legislative proposals and regulatory recalibrations have introduced meaningful uncertainty into the program.
At the federal level, discussions about tax reform have periodically targeted fringe benefits as areas for potential revenue recovery. While commuter benefits have survived several rounds of legislative scrutiny, they are not immune to future modifications. The Tax Cuts and Jobs Act of 2017, for instance, eliminated the employer deduction for providing qualified transportation benefits to employees—a change that reduced the financial incentive for companies to offer these programs voluntarily.
At the state and local level, the picture is more varied. Several states, including California, New York, and New Jersey, have enacted their own commuter benefit mandates requiring employers above a certain size to offer pre-tax transit programs. However, enforcement and compliance rates differ, and not all employers in covered jurisdictions are fully meeting their obligations.
Remote and hybrid work arrangements have introduced another layer of complexity. Employees who no longer commute daily may find their monthly transit elections exceed their actual spending, creating the risk of forfeiture. Conversely, workers who have returned to the office full-time may find that their current elections no longer reflect their actual costs.
Strategies for Maximizing Your Commuter Benefit
Given the combination of underutilization and evolving policy, employees who want to protect and grow this benefit should take a proactive approach.
Review your current enrollment status. If you haven't examined your commuter benefit elections recently, start there. Log into your benefits portal or contact your HR department to confirm whether you're enrolled and at what contribution level.
Calibrate your election to your actual spending. Calculate your average monthly transit and parking costs, then set your election accordingly. Overestimating can lead to forfeiture; underestimating leaves tax savings on the table. Most plans allow you to adjust elections monthly or quarterly.
Understand your employer's program structure. Determine whether your employer subsidizes any portion of your commuting costs or whether the benefit is entirely employee-funded through salary reduction. If a subsidy exists, make sure you're capturing the full amount.
Check for state-level programs. If your employer doesn't offer a commuter benefit program, residents of certain states may have access to state-administered alternatives or may be able to advocate for employer compliance under applicable mandates.
Keep documentation of eligible expenses. While commuter benefits don't require the same level of documentation as medical FSAs, maintaining records of your transit spending can help you reconcile account balances and avoid compliance issues.
The Bigger Picture for Workers and Employers
Commuter benefits represent a relatively simple mechanism for improving employee take-home pay without increasing base compensation costs—making them a compelling tool for employers focused on total compensation strategy. For employees, especially those in urban markets where transit costs can run several hundred dollars per month, the tax savings can be meaningful over the course of a year.
The challenge is that both parties must be engaged for the benefit to function as intended. Employers need to offer the program clearly and communicate its value during open enrollment. Employees need to understand what's available, elect appropriately, and monitor their accounts throughout the year.
As tax policy continues to evolve and workplace norms around commuting remain in flux, staying informed is the most reliable way to protect access to this benefit. For workers looking to reduce their tax burden through legitimate, employer-supported programs, the commuter benefit account deserves a prominent place in their overall financial planning.