One Paycheck Away From Crisis: Understanding the Disability Insurance Coverage Gap
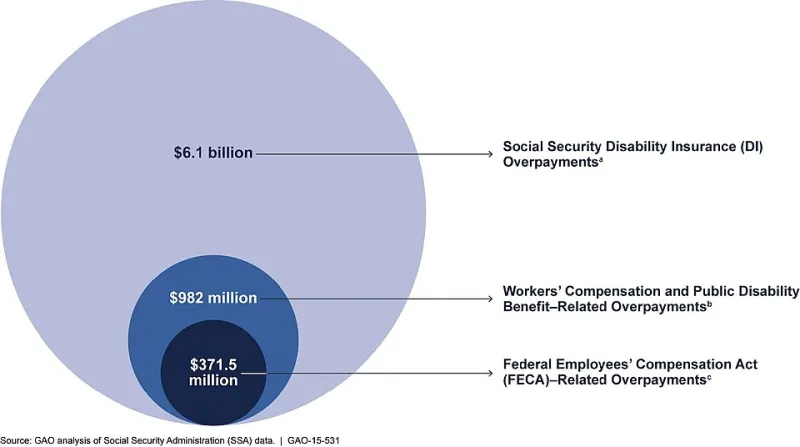
Photo: U.S. Government Accountability Office from Washington, DC, United States, Public domain, via Wikimedia Commons
Most workers spend considerable time thinking about health insurance, retirement contributions, and paid time off. Disability insurance, by contrast, tends to attract little attention—right up until the moment it becomes the only thing that matters.
According to the Social Security Administration, more than one in four workers entering the workforce today will experience a disabling condition before reaching retirement age. Yet surveys consistently show that a significant share of American employees either lack disability coverage entirely or carry policies so limited that a prolonged absence from work would trigger a genuine financial emergency. Understanding why this gap exists—and how to address it—is one of the more important financial decisions an employee can make.
What Disability Insurance Actually Does
At its core, disability insurance replaces a portion of your income when an injury or illness prevents you from working. The benefit is straightforward in concept, but the specifics vary considerably depending on the type of policy and the source of coverage.
Short-term disability (STD) policies typically begin paying benefits within one to two weeks of a qualifying event and continue for a defined period—usually between three and six months. These plans are designed to bridge the gap between the onset of a disability and either the worker's recovery or the activation of a long-term policy.
Long-term disability (LTD) coverage picks up where short-term policies leave off. Benefits may continue for a set number of years or, in some cases, until the policyholder reaches retirement age. Employer-sponsored LTD plans most commonly replace between 50 and 70 percent of pre-disability earnings, though the exact percentage depends on the specific plan design.
Both types serve distinct purposes, and workers who have only one—or neither—are exposed to meaningful financial risk.
The Limits of Employer-Sponsored Coverage
Many employees assume that because their company offers disability insurance, they are adequately protected. That assumption deserves scrutiny.
Employer-provided group disability plans are a valuable starting point, but they come with built-in constraints that employees rarely read until a claim is filed. Several of the most common limitations include:
- Benefit caps. Many group LTD plans place a monthly dollar ceiling on benefits. A worker earning $120,000 annually who assumes their plan will replace 60 percent of their salary may discover that a $5,000 monthly cap applies—leaving a meaningful income gap.
- Definition of disability. Some policies define disability narrowly, requiring that you be unable to perform any occupation, not just your current one. A policy that pays only when you cannot work in any capacity offers far weaker protection than one tied to your specific profession.
- Taxability of benefits. When an employer pays the full premium for a disability policy, the benefits received are generally taxable income. This reduces the effective replacement rate below the stated percentage—sometimes significantly.
- Coverage portability. Group disability coverage typically ends when employment does. A worker who develops a health condition while covered under a group plan and then loses their job may find themselves uninsurable or facing prohibitively expensive individual premiums at the worst possible time.
None of these limitations make employer-sponsored disability insurance without value. They do, however, underscore the importance of reading plan documents carefully rather than assuming coverage is comprehensive.
A Tale of Two Scenarios
To illustrate what is at stake, consider two workers facing similar circumstances but very different outcomes.
Scenario A: Maria is a 38-year-old marketing manager earning $85,000 per year. Her employer provides both short-term and long-term disability coverage at no cost to her. She has never reviewed the policy details. When she is diagnosed with a serious autoimmune condition requiring six months of treatment and recovery, she files a claim. She receives 60 percent of her salary—but because her employer paid the premiums, the benefit is taxable. After taxes, she receives roughly $2,800 per month instead of the $4,250 she anticipated. Her mortgage payment alone is $2,100. The shortfall creates immediate financial strain that compounds over the months of her recovery.
Scenario B: David is a 41-year-old software engineer earning $110,000 annually. His employer offers long-term disability coverage, but no short-term plan. He reviewed his benefits carefully during open enrollment and purchased a supplemental short-term policy on his own, paying the premiums with after-tax dollars. When a back injury sidelines him for four months, his individual policy activates quickly, the benefits arrive tax-free, and he replaces a higher percentage of his income. He returns to work without having touched his emergency savings.
The difference between these two outcomes is not luck. It is preparation.
Evaluating Your Current Coverage
Employees who want to assess their disability protection honestly should begin with a few direct questions:
- Does my employer offer short-term disability coverage? If not, a gap exists between any sick leave balance and the start of long-term benefits. That window can last weeks or months.
- What is the elimination period on my long-term disability plan? This is the waiting period before benefits begin. Common elimination periods range from 60 to 180 days. Workers need enough liquid savings—or short-term coverage—to bridge this interval.
- How does my plan define disability? The distinction between "own occupation" and "any occupation" definitions can be the difference between a functional benefit and one that is nearly impossible to collect.
- What is the monthly benefit cap, and does it align with my actual expenses? If the cap falls short of covering your fixed costs, supplemental coverage is worth considering.
- Who pays the premiums? If your employer covers the full cost, factor in taxation when estimating what you would actually receive.
The Case for Supplemental and Individual Policies
For workers whose employer-sponsored coverage falls short, two primary options exist: supplemental group coverage (if offered through the employer) or individual disability policies purchased directly from an insurer.
Individual policies tend to offer stronger definitions of disability, are portable between jobs, and—because the employee pays premiums with after-tax dollars—generally yield tax-free benefits. The trade-off is cost. Individual disability insurance is not inexpensive, particularly for workers in higher-risk occupations or those with pre-existing health conditions. However, when measured against the potential income loss from a multi-year disability, the premium cost frequently represents a sound financial decision.
Some professional associations and alumni organizations also negotiate group disability rates for members, which can offer a middle path between employer group coverage and fully individual policies.
Social Security Disability: Not a Safety Net You Can Count On
Some workers quietly assume that Social Security Disability Insurance (SSDI) will cover them if private coverage fails. This assumption carries significant risk. SSDI has a rigorous approval process, an average monthly benefit of roughly $1,500, and an application-to-approval timeline that can stretch well beyond a year. SSDI is designed for severe, long-term disabilities and is not a practical substitute for private disability insurance for most working Americans.
Making Disability Insurance a Priority
The next open enrollment period represents an ideal opportunity to review your current disability coverage with fresh eyes. Pull your summary plan description, note the elimination period, benefit cap, and definition of disability, and compare what you would actually receive against what your household requires to function.
If gaps exist, explore supplemental options through your employer or consult with an independent insurance professional about individual policy alternatives. The conversation may feel premature—disability is not something most workers expect to face. But the statistics suggest otherwise, and the financial consequences of being caught without adequate coverage are severe enough that this is one benefit worth understanding thoroughly before it is ever needed.